Student Loan Repayment 2026: New Federal Programs & Savings
Anúncios
Understanding the new federal programs for student loan repayment in 2026 is essential for borrowers to potentially save thousands and navigate their financial obligations efficiently.
Anúncios
Navigating student loan repayment in 2026 can feel like a complex maze, but with recent federal updates, there are significant opportunities for borrowers to save thousands. Are you ready to unlock these new benefits and reshape your financial future?
Understanding the Evolving Landscape of Student Loan Repayment
Anúncios
The world of student loan repayment is constantly shifting, and 2026 brings with it a fresh set of federal programs designed to offer relief and clearer pathways for borrowers. These changes are not just minor tweaks; they represent substantial shifts in how millions of Americans will manage their educational debt. It’s crucial for anyone with federal student loans to stay informed about these updates, as they could dramatically alter repayment strategies and long-term financial health.
Many borrowers have felt overwhelmed by the sheer volume of information and the complexity of existing programs. The new initiatives aim to simplify some aspects while introducing more robust support mechanisms. From revised income-driven repayment options to new forgiveness pathways, the federal government is attempting to address the persistent student debt crisis. Understanding these foundational changes is the first step toward optimizing your repayment plan.
Key Drivers Behind the 2026 Changes
Several factors have influenced the design and implementation of these new federal programs. Economic conditions, persistent calls for student debt relief, and the recognized need for more equitable repayment solutions have all played a role. Policymakers are striving to create a system that is both sustainable for the government and manageable for borrowers, especially those struggling with high debt burdens or fluctuating incomes.
- Economic Impact: High student debt can stifle economic growth, affecting homeownership, small business creation, and overall consumer spending.
- Borrower Advocacy: Continuous efforts from student advocacy groups have highlighted the need for more comprehensive and accessible relief.
- Simplification Goals: A push to streamline application processes and make program eligibility clearer for the average borrower.
Ultimately, these changes reflect a broader effort to make higher education more accessible and its financial aftermath less burdensome. By understanding the motivations behind these programs, borrowers can better appreciate their potential impact and how to best utilize them.
The evolving landscape of student loan repayment in 2026 marks a significant turning point for many. These federal programs are designed to provide tangible relief and clearer pathways, making it essential for borrowers to engage with the new information and adapt their strategies to maximize benefits.
Deep Dive into New Federal Repayment Programs for 2026
As we look towards 2026, several new federal repayment programs are set to take center stage, offering unprecedented opportunities for borrowers. These programs are not merely extensions of old policies but often represent entirely new frameworks designed to address common pain points in student loan management. Understanding the specifics of each program is vital for making informed decisions about your financial future.
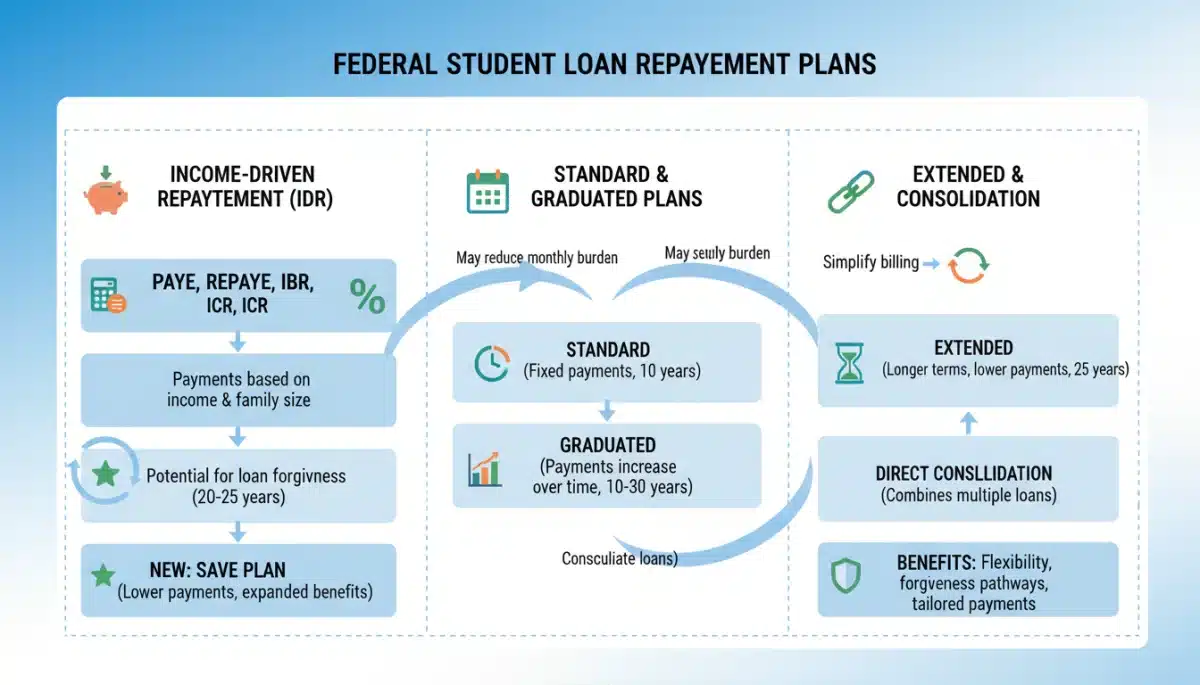
One of the most significant developments is the continued refinement and expansion of income-driven repayment (IDR) plans. While IDR plans have existed for years, the 2026 iterations promise more generous terms, lower monthly payments for many, and faster paths to loan forgiveness. These plans are particularly beneficial for borrowers with lower incomes relative to their debt, providing a safety net that prevents default and offers a clear path out of debt.
Specific Program Highlights and Benefits
Among the new offerings, particular attention should be paid to programs that either reduce monthly payments or accelerate loan forgiveness. Some initiatives might combine elements of both, providing a dual benefit. It’s important to differentiate between programs that offer immediate payment relief and those that provide long-term forgiveness, as your personal financial situation will dictate which is most advantageous.
- Enhanced Income-Driven Repayment (IDR) Plans: Expect lower discretionary income percentages used for payment calculations, potentially leading to significantly reduced monthly bills.
- Streamlined Forgiveness Pathways: New rules may simplify the process for public service loan forgiveness (PSLF) and IDR forgiveness, reducing administrative burdens and clarifying eligibility.
- Targeted Debt Relief Initiatives: Certain programs may be introduced to address specific borrower groups, such as those with very old loans or those who never completed their degrees.
These programs are designed with the borrower in mind, aiming to make student loan debt less of a lifelong burden. By carefully evaluating each option, you can align your repayment strategy with the benefits offered by these new federal initiatives.
The new federal repayment programs for 2026 offer a renewed sense of hope for many student loan borrowers. By delving into the details of these initiatives, individuals can identify the best pathways to manage their debt, reduce their financial stress, and work towards a more secure financial future.
Financial Impact: How These Programs Can Save You Thousands
The introduction of new federal student loan repayment programs in 2026 isn’t just about minor adjustments; it’s about creating tangible financial relief that could save borrowers thousands of dollars over the life of their loans. The financial impact of these changes can be profound, freeing up income for other essential needs, investments, or simply improving quality of life.
For many, reduced monthly payments mean more disposable income. This can be critical for individuals struggling to meet daily expenses, save for a down payment on a home, or start a family. The ripple effect of lower student loan payments extends beyond just the loan itself, influencing overall financial stability and personal economic growth.
Furthermore, accelerated paths to loan forgiveness can eliminate entire balances, representing tens of thousands of dollars that borrowers would otherwise have to repay. This can be life-changing, allowing individuals to pursue career paths that might have been financially unfeasible or to achieve long-term financial goals much sooner.
Illustrative Scenarios of Savings
To truly grasp the potential savings, let’s consider a few hypothetical scenarios. Imagine a borrower with $40,000 in student debt earning $50,000 annually. Under previous repayment plans, their monthly payment might have been substantial, leaving little room for savings. With new IDR plans, their payment could drop significantly, potentially by hundreds of dollars per month. Over a year, this could translate to thousands in savings.
- Scenario 1 (Lower Monthly Payments): A borrower’s payment drops from $400 to $150 per month, saving $3,000 annually.
- Scenario 2 (Earlier Forgiveness): A borrower qualifies for forgiveness after 20 years instead of 25, saving five years of payments and potentially tens of thousands in interest.
- Scenario 3 (Interest Subsidies): New programs might prevent interest capitalization, meaning the loan balance doesn’t grow even when payments are low, saving thousands in accrued interest.
These scenarios highlight how even seemingly small adjustments in program rules can lead to substantial financial benefits. It’s not just about paying less each month; it’s about the cumulative effect of these savings over the long term.
The financial impact of the 2026 federal repayment programs is poised to be a game-changer for countless student loan borrowers. By understanding and leveraging these opportunities, individuals can realize significant savings, improve their cash flow, and accelerate their journey towards financial freedom.
Eligibility Requirements and How to Apply for New Programs
Understanding the eligibility requirements for the new federal student loan repayment programs in 2026 is the crucial next step after recognizing their potential benefits. While the goal is to make these programs more accessible, specific criteria will still apply, and borrowers need to be aware of them. Generally, these programs are designed for federal student loans, but the exact types of loans covered can vary.
Most federal student loans, including Direct Loans (subsidized, unsubsidized, PLUS), are typically eligible for income-driven repayment plans and various forgiveness programs. However, older loan types, such as Federal Family Education Loans (FFEL) or Perkins Loans, might require consolidation into a Direct Consolidation Loan to qualify for the most favorable terms of the new programs. It’s vital to confirm your loan types before proceeding.
Navigating the Application Process
The application process for federal student loan programs is primarily managed through the U.S. Department of Education’s Federal Student Aid (FSA) website. While the specific forms and steps may evolve by 2026, the general framework is likely to remain consistent. Borrowers will typically need to provide income and family size information to apply for income-driven plans, and employment verification for public service loan forgiveness.
- Gather Documentation: Have your tax returns, pay stubs, and loan account information readily available.
- Use the FSA Website: The official Federal Student Aid website (studentaid.gov) is the primary portal for applications and information.
- Contact Your Loan Servicer: Your loan servicer can provide guidance and assist with the application process, though it’s always wise to cross-reference information with official FSA resources.
It’s also important to be proactive. Don’t wait until the last minute to explore these options. Start researching eligibility and application procedures well in advance of 2026 to ensure you can take full advantage of the programs as soon as they become available or are fully implemented.
Successfully navigating the eligibility and application process for the new federal student loan programs is key to unlocking their benefits. By understanding what is required and proactively preparing, borrowers can ensure they are well-positioned to access the financial relief available.
Common Pitfalls and How to Avoid Them in 2026
While the new federal student loan repayment programs in 2026 offer significant advantages, borrowers must be aware of common pitfalls that can hinder their ability to benefit fully. Navigating these complexities requires careful attention to detail and a proactive approach. Understanding potential missteps can save you time, money, and frustration in the long run.
One of the most frequent issues is misunderstanding program eligibility. Borrowers might assume they qualify for a specific program without thoroughly checking the criteria, leading to rejected applications or enrollment in a less advantageous plan. Another common pitfall is failing to recertify income and family size annually for income-driven repayment plans, which can result in higher payments or interest capitalization.
Strategies for Successful Program Enrollment
Avoiding these common issues involves a combination of careful research, diligent record-keeping, and timely action. Don’t rely solely on word-of-mouth; always verify information through official sources like the Federal Student Aid website or your loan servicer.
- Verify Loan Types: Confirm your loans are federal and eligible for the programs you’re interested in. Consolidate if necessary.
- Understand Annual Requirements: Mark your calendar for annual income recertification deadlines for IDR plans.
- Keep Detailed Records: Maintain copies of all correspondence, application submissions, and payment confirmations.
- Beware of Scams: Be cautious of third-party companies promising quick fixes or charging fees for services that are free through the Department of Education.
Furthermore, it’s crucial to understand the long-term implications of your chosen repayment plan. While lower monthly payments are appealing, ensure you understand how interest accrues and how different plans affect the total amount repaid over time. Sometimes, a slightly higher payment now can lead to significant savings later.
By being aware of common pitfalls and employing strategic planning, borrowers can effectively navigate the new federal student loan repayment programs in 2026. This proactive approach ensures maximum benefit and a smoother path toward managing student debt.
Long-Term Strategies for Student Loan Management Beyond 2026
While the immediate focus is on the new federal student loan repayment programs in 2026, effective student loan management requires a long-term perspective. These programs are tools, but how you integrate them into your broader financial strategy will determine your ultimate success. Thinking beyond the initial benefits and planning for future financial shifts is crucial for sustained debt freedom.
Your income, career path, and family situation are likely to change over time, and your student loan strategy needs to adapt accordingly. What works best today might not be optimal in five or ten years. Regularly reviewing your repayment plan, especially when significant life events occur, is a cornerstone of responsible student loan management.
Integrating Loans into Your Financial Ecosystem
Student loans don’t exist in a vacuum; they are part of your entire financial ecosystem. This means considering how your loan payments interact with other financial goals, such as saving for retirement, purchasing a home, or building an emergency fund. A holistic approach ensures that managing your student debt doesn’t derail other important aspects of your financial life.
- Regular Plan Review: Re-evaluate your repayment plan annually or whenever your financial situation changes significantly (e.g., job change, marriage, new child).
- Emergency Fund: Build and maintain an emergency fund to cover unexpected expenses, preventing reliance on forbearance or deferment unless absolutely necessary.
- Debt Snowball/Avalanche: Consider using strategies like the debt snowball or avalanche method for other debts, allowing you to focus more aggressively on student loans once other high-interest debts are cleared.
- Financial Literacy: Continuously educate yourself on personal finance to make informed decisions about your money, including student loan management.
Ultimately, the goal is not just to repay your loans but to do so in a way that supports your overall financial well-being and future aspirations. The new programs in 2026 provide a powerful starting point, but sustained effort and strategic planning will be your greatest allies.
Long-term student loan management extends far beyond the immediate benefits of new federal programs. By adopting a comprehensive and adaptable financial strategy, borrowers can navigate their debt effectively, integrate it into their broader financial goals, and ultimately achieve lasting financial security.
| Key Program | Brief Description |
|---|---|
| Enhanced IDR Plans | New income-driven repayment plans offering lower monthly payments and potentially faster forgiveness. |
| Streamlined Forgiveness | Simplified pathways for Public Service Loan Forgiveness (PSLF) and IDR forgiveness, reducing administrative hurdles. |
| Targeted Debt Relief | Specific initiatives aimed at particular borrower groups, such as those with older loans or incomplete degrees. |
| Interest Subsidies | Provisions to prevent interest capitalization, helping to keep loan balances from growing under certain conditions. |
Frequently Asked Questions About 2026 Student Loan Repayment
The biggest changes involve more generous income-driven repayment plans with lower discretionary income percentages, leading to reduced monthly payments for many. There are also efforts to streamline loan forgiveness processes and potentially introduce targeted relief for specific borrower groups.
Eligibility generally applies to federal student loan borrowers, primarily those with Direct Loans. Borrowers with older loan types like FFEL or Perkins Loans may need to consolidate them into a Direct Consolidation Loan to qualify for the most beneficial new programs.
You can save money through lower monthly payments, which free up cash flow. Additionally, faster paths to loan forgiveness can eliminate your remaining balance, saving you tens of thousands in principal and interest. Interest subsidies can also prevent your loan balance from growing.
Start by verifying your loan types on studentaid.gov. Stay informed about official announcements from the Department of Education, gather your financial documents (tax returns, pay stubs), and contact your loan servicer if you have specific questions about your account.
Yes, common pitfalls include misunderstanding eligibility, failing to recertify income annually for IDR plans, and falling victim to scams from third-party companies. Always use official government channels for information and applications to avoid these issues.
Conclusion
Navigating student loan repayment in 2026 presents a unique opportunity for borrowers to significantly improve their financial standing. The new federal programs are designed to offer substantial relief, from reduced monthly payments to clearer paths toward loan forgiveness. By understanding these updates, proactively checking eligibility, and carefully managing the application process, borrowers can unlock thousands in savings and achieve greater financial stability. It’s crucial to stay informed, utilize official resources, and integrate these programs into a comprehensive long-term financial strategy to truly harness their benefits.